
Most hospice facilities need professional liability (malpractice), general liability, workers’ compensation, commercial property, and cyber liability. Hospices whose staff visit patients at home also need auto coverage, and larger organizations often add business interruption, employment practices liability, and directors and officers coverage. The right mix depends on your size, services, and where care is delivered.
Running a hospice is a balancing act between compassion, patient care, and operational security. Behind the scenes, every hospice navigates risks from patient incidents and employee injuries to regulatory reviews and cyber threats. One unaddressed risk can trigger a costly lawsuit or disrupt care, so understanding each coverage, and where the gaps are, matters as much as buying it.
Key takeaways
- Professional liability is the core coverage for hospice care, because most serious claims involve the care itself.
- Staff who drive to patients’ homes create auto exposure that general liability does not cover.
- Check abuse and molestation, cyber, and coverage for the medical director before you buy.
- Compare policies on who is covered, claims-made versus occurrence terms, and limits, not just price.
The Core Coverages a Hospice Facility Needs
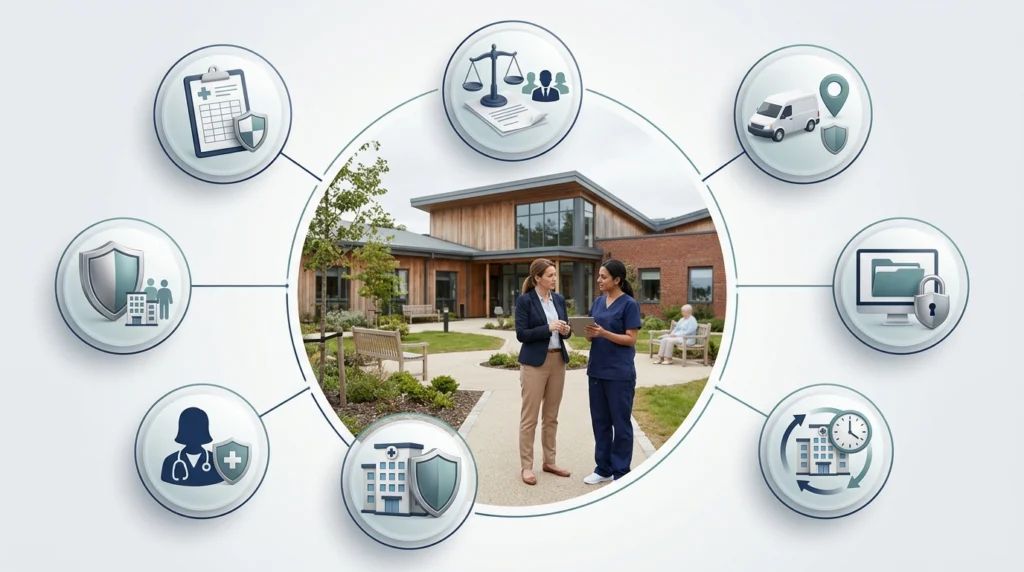
Each policy protects a different part of the operation. Together they form a layered program:
| Coverage | What it protects | Hospice example |
|---|---|---|
| Professional liability (malpractice) | Claims that care caused harm | A medication error or a missed change in condition |
| General liability | Injuries and property damage to others | A family member slips in a hallway |
| Workers’ compensation | Employee injuries and illnesses | A nurse injures her back moving a patient |
| Commercial property | Building, medical equipment, and supplies | A kitchen fire damages the facility |
| Business interruption | Lost income during a covered closure | Operations pause while fire damage is repaired |
| Cyber liability | Data breaches and ransomware | Patient records are exposed in a hack |
| Commercial auto / hired and non-owned auto | Accidents during home visits | A nurse crashes while driving to a patient |
| Employment practices and D&O | Employee claims and leadership decisions | A wrongful termination lawsuit |
Professional Liability and the Medical Director
Professional liability is where hospice claims are most serious, because they involve symptom management, medications, and end-of-life decisions. Confirm who the policy actually covers: employed nurses and aides, volunteers, the medical director, and any contracted physicians. Medical directors are sometimes covered under the hospice’s policy and sometimes required to carry their own malpractice insurance, so check before a claim forces the question.
Coverage for Staff Who Visit Patients at Home
Many hospices deliver care in patients’ homes, which means staff spend hours on the road. If nurses or aides drive their own cars, their personal auto policy protects them, not the hospice. Hired and non-owned auto coverage protects the organization if an employee’s accident leads to a lawsuit. Hospices that own vehicles need commercial auto. Home health agencies face the same exposure, along with many of the same professional liability risks.
Cyber Liability and Patient Records
Hospices hold medical histories, medication lists, and billing data. A lost laptop or a ransomware attack can trigger notification costs, investigations, and lawsuits under HIPAA. Cyber liability helps pay for forensic work, notification, and legal defense, which most malpractice policies do not cover.
Can a Hospice Use a Business Owner’s Policy?
A business owner’s policy bundles general liability, property, and business interruption coverage, but many insurers limit BOP eligibility for healthcare facilities. Larger hospices usually build a package of separate policies instead. Our comparison of general liability vs. a business owner’s policy explains the tradeoffs.
What Hospice Coverage Often Leaves Out
Knowing the gaps matters as much as knowing the coverage. Depending on the policy, you may need separate protection or endorsements for:
- Abuse and molestation allegations: frequently excluded or limited in standard liability policies
- Employee injuries: handled by workers’ compensation, not general liability
- Data breaches: usually require a separate cyber policy
- Intentional acts: not covered by any liability policy
- Regulatory fines and penalties: often excluded, even when defense costs are covered
Hospice providers
Not sure what your current policy leaves out?
How to Compare Hospice Care Professional Insurance Policies
Two quotes can look similar and protect very different things. Before you buy or renew, compare:
- Who is covered: employees, volunteers, the medical director, and contracted clinicians.
- Claims-made or occurrence: claims-made policies cover claims filed while the policy is active, so ask about tail coverage if you switch carriers.
- Limits: per-claim and aggregate limits that match your patient census and contracts.
- Exclusions and sublimits: especially abuse and molestation, cyber, and regulatory proceedings.
- Defense costs: whether legal defense reduces your available limits.
- Where care happens: coverage for home visits, facility care, and any inpatient units.
Free coverage review
Compare your hospice coverage before you renew.
- Medical director coverage
- Abuse and molestation
- Hired and non-owned auto
- Cyber and HIPAA
Hospice Risk Management Checklist

Insurance alone isn’t enough. A risk management checklist helps administrators reduce claims before they happen:
- Conduct regular safety audits for patient rooms, hallways, and outdoor spaces.
- Implement infection control protocols, particularly for immunocompromised patients.
- Train staff on patient handling, emergency procedures, and equipment use.
- Keep accurate documentation for all patient interactions and incident reports.
- Protect electronic health records with strong cybersecurity measures.
- Review insurance coverage every year and whenever services or locations change.
Example: One Incident, Several Policies
Imagine a 50-bed hospice where a kitchen fire damages part of the building and a nurse injures her back helping evacuate a patient. Commercial property pays for the fire damage, business interruption helps cover lost income while repairs are made, and workers’ compensation covers the nurse’s medical care. If a visitor is hurt during the evacuation, general liability responds. One event, four policies, which is why hospices review coverage as a whole rather than one policy at a time.
Building the Right Coverage for Your Hospice
Every hospice is different. A small home-based program and a facility with inpatient beds face different risks, so the right coverage starts with how and where you deliver care. Review your policies together each year, and whenever you add services, staff, or locations, so gaps don’t open between them.
McDonough Insurance Services has helped California healthcare providers manage risk for decades. If you’d like a second look at how your policies fit together, we can review your hospice insurance against the care you provide and where you provide it.
Frequently Asked Questions
Final Thoughts
At least once a year, and whenever you add services, locations, staff, or home-visit programs.