A certificate of liability insurance (COI) is a one-page document that proves your business carries liability insurance. It summarizes the insured business, the insurance company, coverage types, limits, and policy dates, and it is usually requested by a client, landlord, or general contractor before work or a lease begins.
A COI makes insurance verification easier, but it is not the insurance policy itself. It also does not automatically give coverage to everyone named on the document. Understanding what a certificate shows, who the certificate holder is, and how it relates to your actual policy can help prevent contract delays and costly misunderstandings.
Key takeaways
- A certificate of liability insurance (COI) is a one-page summary, usually on the ACORD 25 form, that proves your business carries liability coverage.
- Being listed as a certificate holder does not give coverage. Additional insured status requires an endorsement on the policy.
- A COI shows coverage for the dates listed, but it doesn’t guarantee a specific claim will be paid.
- Send the client’s full insurance requirements to your agent, and check names, limits, and dates before you submit.
What Is a Certificate of Liability Insurance?
A certificate of liability insurance is a document used to provide evidence of business insurance coverage. For a small business, proof of insurance usually means a COI. It is commonly requested before a company begins work for a client, enters a commercial lease, joins a construction project, or signs a contract with another business.
Rather than asking the other party to review an entire insurance policy, a certificate provides a convenient summary of the information most relevant to the relationship. A general contractor, for example, may request one from a subcontractor before allowing work to begin.
What Does a Certificate of Insurance Look Like?
Most liability certificates in the U.S. use the ACORD 25 form, a standard one-page layout created by ACORD, the organization that maintains insurance industry forms. Agents and carriers fill it in from your policy details, so certificates from different insurers look nearly the same.
Information on a Certificate of Liability Insurance
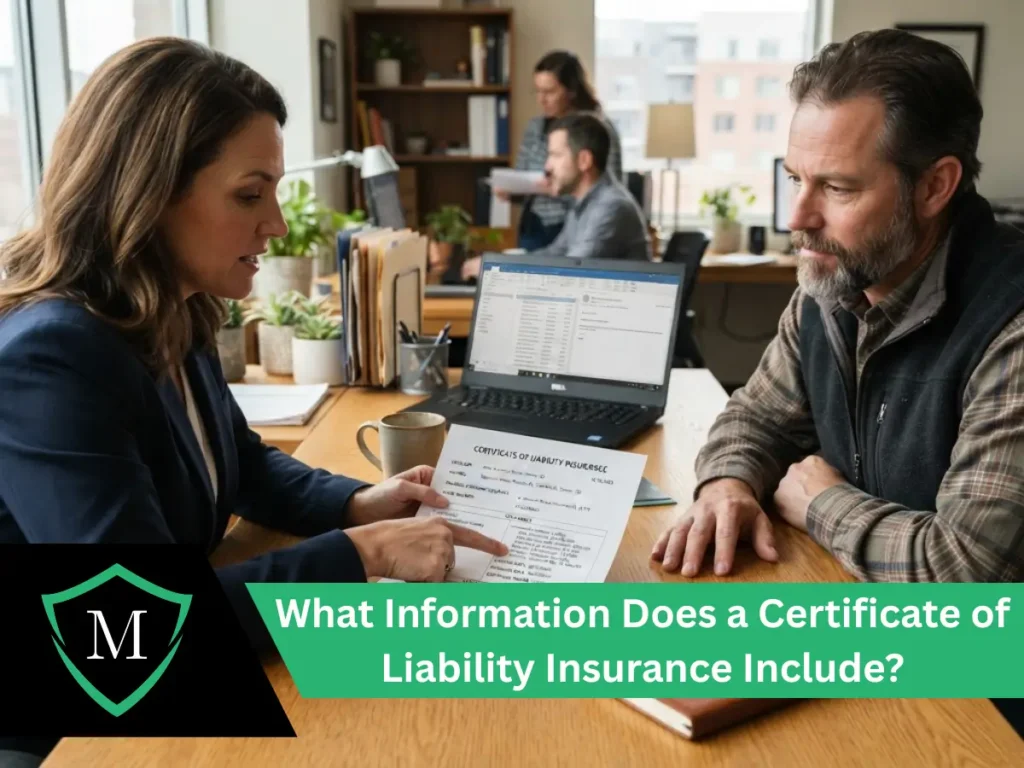
A certificate puts essential insurance details into an easy-to-review format. It generally shows:
- Named insured: the business or individual who owns the policy
- Producer and insurers: the insurance agency and the companies providing coverage
- Coverage types: general liability, commercial auto, umbrella or excess, and workers’ compensation and employers’ liability
- Limits and policy dates: the amounts of coverage and the effective and expiration dates
- Description of operations: room for project, location, or contract details
- Certificate holder: the person or organization receiving the certificate
These details matter when a business operates under more than one legal name. If a contract identifies ABC Construction LLC but the certificate shows a different entity, the requesting party may question whether it satisfies the agreement. Dates matter too: a certificate showing an expired policy period may not satisfy a current contract, even if you have since renewed. Depending on the business, it may also list workers’ compensation or professional liability coverage.
What Is a Certificate Holder for Insurance?
A certificate holder is the person or organization receiving the certificate as evidence that another party has insurance. For example, a property owner may require a contractor to provide a certificate before allowing work at a building, and the owner is listed as the certificate holder. Being listed as a certificate holder does not automatically make that party an insured under the policy.
| Certificate Holder | Additional Insured |
|---|---|
| Receives the insurance certificate | May receive certain coverage rights under the policy |
| Does not automatically receive coverage | Coverage depends on policy language or an endorsement |
| Relates to insurance documentation | Relates to rights under the insurance policy |
| Common for clients, landlords, and contractors requesting proof | Common when a contract requires another party to receive protection |
If a contract requires additional insured status, simply putting that party’s name on the certificate is not enough. The policy needs an endorsement that grants it. The National Association of Insurance Commissioners explains that an endorsement can modify a policy by adding, changing, restricting, or excluding coverage.
What a COI Proves, and What It Doesn’t
A COI proves that the listed policies were in force for the dates shown. It does not guarantee that a particular claim will be covered. The underlying policy decides that through its definitions, exclusions, conditions, limits, and endorsements. Seeing a general liability limit on a certificate does not mean every loss involving the business is covered, and a certificate cannot create coverage the policy does not provide.
Free contract review
Send us the contract. We’ll check your coverage against it.
- Limits and coverage types
- Additional insured endorsements
- Waiver of subrogation
- Named insured and policy dates
Common COI Requirements in Contracts
Insurance requirements usually come from a contract, lease, or project agreement, and they vary from client to client. Common requests include:
- General liability limits: often a set per-occurrence and aggregate amount
- Additional insured status: naming the client on your policy through an endorsement
- Waiver of subrogation or primary and noncontributory wording: provisions that affect how claims are shared
- Workers’ compensation and employers’ liability: proof that your crew is covered
A COI Example
Imagine a plumbing contractor hired for a commercial renovation. Before work begins, the property owner requests proof of liability insurance. The contractor sends the owner’s requirements to its agent, who issues a certificate showing the insurer, coverage, limits, and policy period. If the contract requires a higher limit than the contractor carries, or additional insured status the policy does not provide, the problem surfaces before work starts instead of after a claim.
How to Get a Certificate of Insurance
Most businesses request a certificate through their insurance agent, broker, or carrier:
- Send the full request. Forward the contract’s insurance section rather than asking for a generic certificate.
- Provide exact details. Include the certificate holder’s legal name and address and any project information.
- Flag special requirements. Mention additional insured status or endorsements so your agent can confirm the policy supports them.
- Ask early. A standard certificate is usually quick, but one that needs a policy change may take longer.
Business insurance
Need a certificate for a new contract?
How to Review a Certificate of Liability Insurance
Don’t assume a certificate is correct because it came from an insurance professional. Check that the named insured matches the legal business name in the contract, the limits and coverage types meet the requirements, the policy dates are current, and the certificate holder’s name and address are spelled correctly. Request a new certificate whenever your policy renews or changes, because an older one may no longer reflect your coverage.
Requesting COIs From Vendors and Subcontractors
The same checks apply when you are the one asking. Hotels, property managers, and general contractors often require a certificate of insurance from vendors such as cleaning and maintenance companies before they start. A typical request asks for general liability, workers’ compensation, and commercial auto if they drive on site, plus additional insured status for your business. Keep the certificates on file and track expiration dates, which matters most for contractors managing several subs.
If your business needs help meeting a contract’s insurance requirements, McDonough Insurance Services can review the coverage behind your certificates and confirm your insurance matches what clients ask for.
Frequently Asked Questions
Final Thoughts
COI stands for certificate of insurance, a summary document businesses use to prove their coverage to clients, landlords, and partners.
An LLC requests a certificate the same way any business does, whenever a client or landlord asks for proof of coverage. The certificate must show the LLC’s exact legal name.
Usually not. Most agents and carriers issue certificates at no extra charge, although adding an endorsement such as additional insured status may change your premium.
Disclaimer: This article is for general informational purposes only and is not legal, tax, or insurance advice. Coverage options, requirements, and pricing vary by business, industry, location, and carrier, and policy terms always govern. Reading this article does not create coverage or an advisory relationship. For guidance on your specific situation, contact McDonough Insurance Services at 949-361-8471 or request a quote. Our licensed team has helped California businesses find the right coverage since 1981.