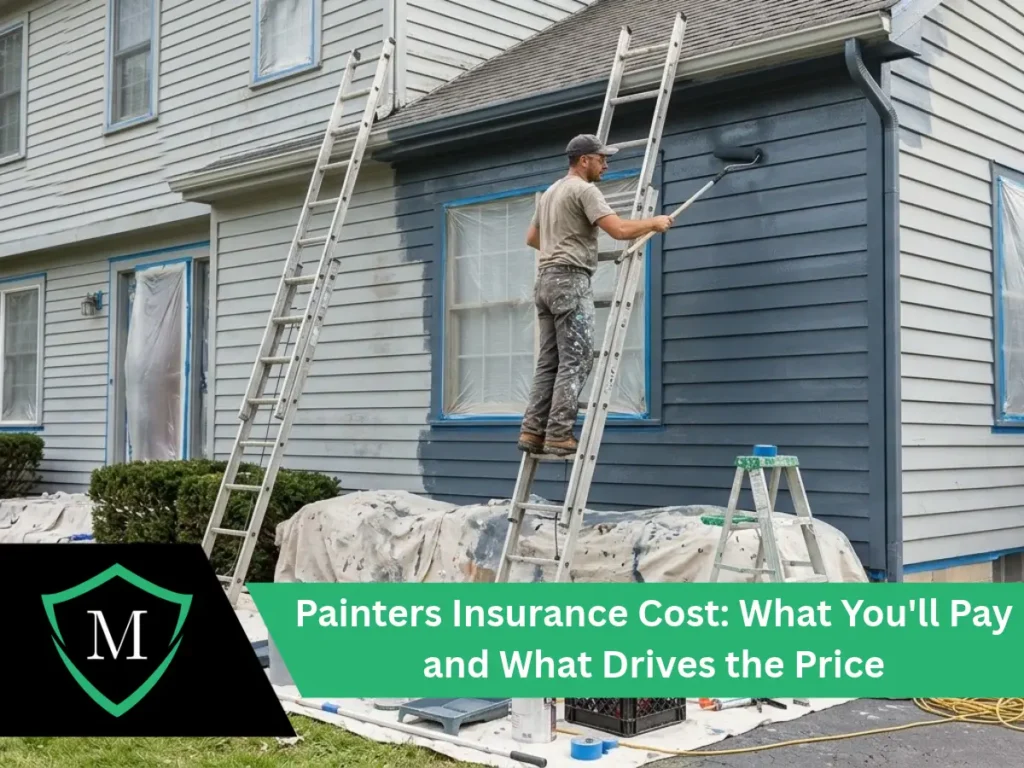
Painters insurance cost depends on seven main factors: crew size and payroll, the type of work you do, how high you work, lead paint and older buildings, your claims history, the limits your contracts require, and your vehicles and equipment. A solo painter doing residential interiors usually pays far less than a commercial crew working on multi-story buildings, so painting insurance cost varies widely from one business to the next.
You’ve built a painting business on skill, reputation, and word of mouth. Insurance is the last thing on your mind until a spill ruins a customer’s hardwood floor, a worker falls off a ladder, or a client blames your prep work for damaging a wall. This guide explains what drives the price, so you can budget accurately and avoid paying for gaps.
Key takeaways
- Crew size is the biggest single cost driver, because workers’ compensation is priced on payroll.
- Commercial jobs, work at height, and pre-1978 buildings with lead paint all raise premiums.
- California requires workers' comp once you hire, and all licensed contractors must carry it starting January 1, 2028.
- Accurate payroll, documented safety practices, and annual reviews keep your rate in check without leaving gaps.
How Much Does Painters Insurance Cost?
There is no single price for every painter, because insurers price each business on its own risk. Online averages are built on a standard business profile, so a figure for a one-person residential painter says little about a commercial crew with three trucks. The most reliable number is a quote based on your payroll, your work, and the limits your clients require.
Liability pricing follows the same logic across trades. Our guide to general liability insurance cost explains how insurers rate it.
7 Factors That Set Your Premium
Insurers look at the same handful of details every time they price a painting business. Some, like crew size and the type of jobs you take, move your premium far more than others. Here’s what each factor means for your rate, starting with the one that matters most.
1. Crew Size: How It Affects Painting Insurance Premiums
Crew size is the biggest single driver of cost. Workers’ comp is priced on payroll, so every hire adds a premium directly. More people on site also means more exposure to property damage and injury claims, which raises general liability, and a bigger crew usually means more vehicles on your commercial auto policy. Once you hire even one employee, workers’ comp becomes mandatory in California, which is where most painting businesses see the biggest jump.
2. Residential vs. Commercial Work
Commercial painting usually costs more to insure than residential work, because contracts are larger, sites are busier, and clients often require higher limits. Painters who focus on residential interiors typically see the lowest premiums in the trade.
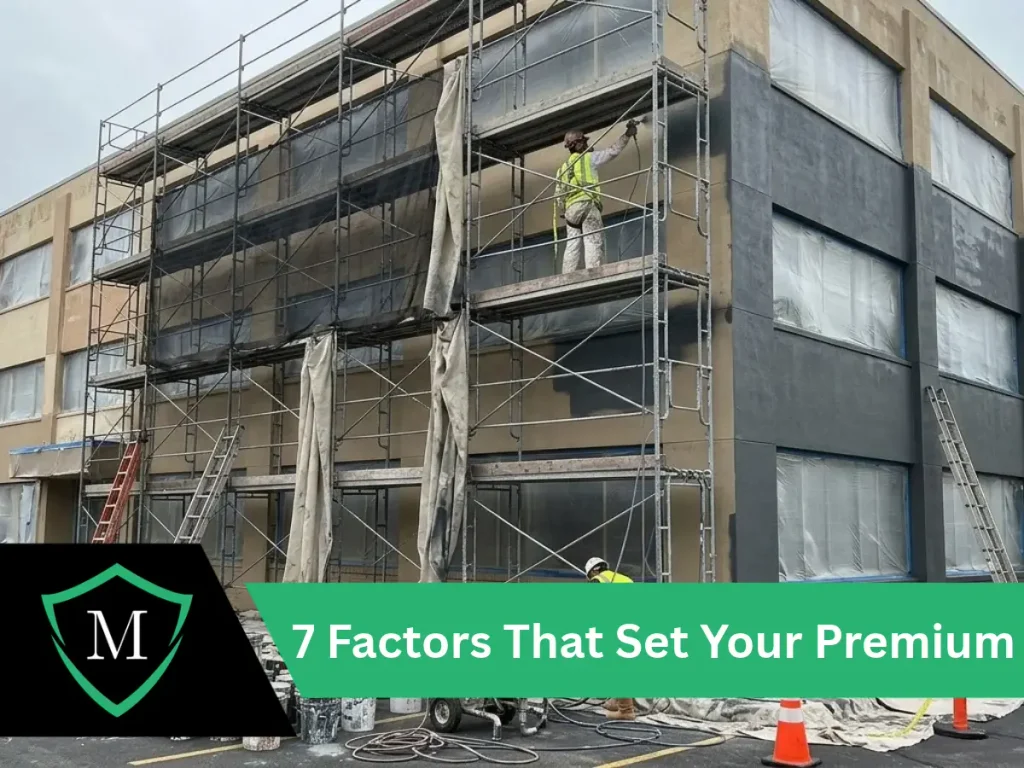
3. Working at Heights
Ladders, scaffolds, and lifts raise the risk of serious injuries, which shows up in workers’ comp pricing. OSHA’s fall prevention resources cover the hazards painting crews face on multi-story work.
4. Lead Paint and Older Buildings
Sanding or scraping paint in older homes can disturb lead, which creates exposure claims that general liability often excludes. The EPA’s lead program explains the lead-safe work practices required for renovation, repair, and painting. Painters who regularly work on older buildings may need pollution liability coverage, which adds cost.
5. Claims History
A history of property damage or injury claims raises premiums, while a clean record helps. Documented safety training and equipment inspections can help show insurers you manage risk.
6. Coverage Limits and Deductibles
Higher limits cost more, and a higher deductible can lower your premium but raises what you pay after a claim. General contractors and property managers usually set minimum limits in the contract; our guide to general contractor insurance requirements shows the limits public agencies commonly require.
7. Vehicles and Equipment
Every work truck adds to your commercial auto premium, and sprayers, ladders, and scaffolding that travel between jobs need tools and equipment coverage. The more you have, the more you insure.
How Workers' Comp Is Priced for Painters
Workers’ comp premiums are based on your payroll and the job classification assigned to painting work, then adjusted for your claims experience. For context, the California Department of Insurance approved an average advisory pure premium rate of $1.65 per $100 of payroll effective September 1, 2026. That is a statewide benchmark across all classifications, not a painting rate or a quote.
At the end of the policy year, your insurer audits actual payroll. If it was higher than estimated, you owe more. Calling helpers independent contractors doesn’t settle the question: California looks at whether you control how they work, as the Department of Industrial Relations explains, and our 1099 vs. W-2 guide covers the audit risk.
California Requirements That Affect Your Cost
- Licensing: painting work falls under the C-33 Painting and Decorating Contractor classification.
- Contractor license bond: every licensee needs a $25,000 contractor license bond, which adds a small annual cost.
- Workers’ compensation: required once you have an employee, and scheduled for all licensed contractors on January 1, 2028, with or without employees.
- LLC liability: contractors licensed as an LLC must carry at least $1 million in liability insurance, increasing with personnel up to $5 million.
Free contract review
Send us the contract. We’ll check your coverage against it.
- Limits and coverage types
- Additional insured endorsements
- Waiver of subrogation
- Named insured and policy dates
What Self-Employed Painters Typically Carry
Working solo gives you more flexibility, but you still need coverage. Most independent painters carry general liability, since clients ask for a certificate before work starts, and commercial auto if they drive to job sites. Without employees, workers’ comp isn’t required for yourself today, but plan for it the moment you bring on a helper, and for the 2028 change.
How to Lower Your Insurance Cost Without Gaps
- Work with a broker who knows contractors. The right carrier and class code matter more than the lowest quote.
- Estimate payroll honestly. Overestimating means overpaying; underestimating means an audit bill at year’s end.
- Document your safety practices. Fall protection plans, inspection logs, and training records help at underwriting.
- Bundle where it makes sense. A business owner’s policy can combine liability and property for eligible businesses.
- Confirm completed operations coverage. Some low-cost policies limit it, and peeling-paint claims often arrive after the job is done.
- Review coverage every year, especially when your crew grows or you move into commercial work.
Business insurance
Need a certificate for a new contract?
What It Costs to Go Without Coverage
Property Damage Without General Liability
A sprayer malfunction coats a client’s custom cabinets in the wrong finish. With general liability, the policy pays the covered claim minus your deductible. Without it, you pay to strip and refinish the cabinets, lose the invoice, and may face a lawsuit.
A Worker Injury Without Workers’ Comp
A painter falls from a ladder and can’t work for weeks. Workers’ comp pays medical bills and partial lost wages. Without it, those costs fall on you personally.
A Contract Lost for Lack of a Certificate
A property manager offers recurring work but requires a certificate of insurance showing liability and workers’ comp. Without coverage, the contract goes to a competitor, and that lost revenue usually outweighs the premium.
McDonough Insurance Services works with painting contractors across California. When you’re ready to compare options built around your crew and contracts, explore our painters insurance coverage.
Get the Right Rate Before the First Coat
Insurance cost comes down to seven things: your crew size and payroll, the kind of jobs you take, how high you work, lead paint exposure, your claims history, the limits your contracts require, and the vehicles and equipment you insure. Workers’ comp is usually the biggest variable once you hire, and California’s 2028 rule will extend it to every licensed contractor. Accurate payroll, documented safety practices, and an annual review keep your premium fair without leaving gaps.
McDonough Insurance Services has helped California contractors for over 40 years. If you’d like a quote built around your crew, your work, and the contracts you bid, explore our painters insurance options or call 949-361-8471.